Table of Contents
- Why Roof Repair Bills Balloon Past the First Estimate
- The Roof Inspection Checklist for Homeowners That Catches Problems Early
- How Homeowners Insurance Roof Coverage Ohio Works for Storm Damage
- How to Choose a Reputable Roofer in Cincinnati
- What Actually Drives Roof Repair Costs Up or Down
- Preventative Maintenance That Keeps Small Fixes From Becoming Big Bills
- Frequently Asked Questions
Last Updated: September 11, 2026
Why Roof Repair Bills Balloon Past the First Estimate
Roof repair costs rarely explode because of one catastrophic failure. They balloon because small, cheap problems sit unattended until water reaches the decking, insulation, and ceilings below. At DGK Home Solutions, we’ve observed a common pattern over 20 years: a homeowner calls about a stain on the ceiling, and the fix has quietly grown from a patch into a full tear-off.
Here’s the uncomfortable math behind that. A cracked flashing boot around a vent pipe is a minor repair. Let it leak for two winters and you’re replacing rotted sheathing, saturated underlayment, and possibly a section of drywall. The labor is the same; the materials and scope are not.
That’s the entire case for avoiding surprise roof repair costs: catch the small stuff early, and the big bill never arrives. Below, we’ll show you exactly what to inspect, when to call a professional, and how insurance and contractor choice change what you actually pay.
If you’ve ever opened a roofing estimate and felt the number was invented on the spot, this guide is for you.
The Roof Inspection Checklist for Homeowners That Catches Problems Early
A roof inspection checklist for homeowners is a seasonal, ground-level routine that documents visible wear before it becomes structural. You don’t need to climb anything. You need a pair of binoculars, a phone camera, and fifteen minutes four times a year.
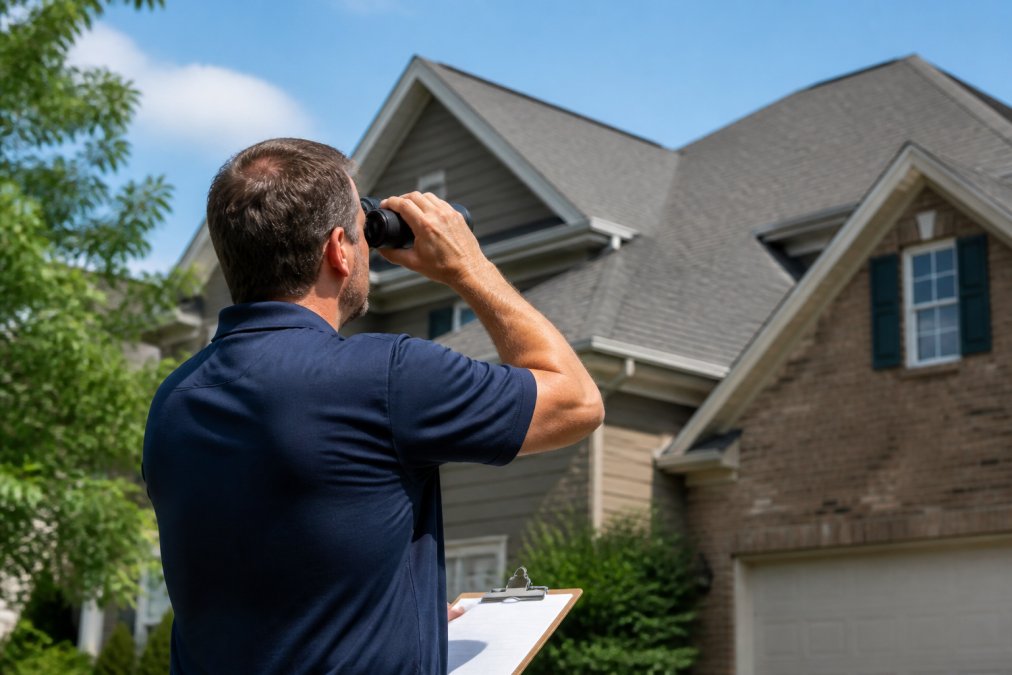
What to Check From the Ground Each Season
Start with the easy stuff, because most leaks announce themselves long before they reach your ceiling.
- Look for shingles that are curling, cracked, or missing entirely
- Check for granules collecting in gutters or at downspout outlets
- Inspect flashing around chimneys, vents, and skylights for gaps or rust
- Scan the fascia and soffit for soft spots, peeling paint, or water stains
- Note any sagging along the roofline
- After a storm, photograph anything that looks different
In Ohio, the freeze-thaw cycle does most of the damage (weather.gov). Water works into a hairline crack, freezes overnight, expands, and widens the gap. Repeat that across a winter and a minor issue becomes a leak.
What Only a Professional Should Check
Some things you genuinely cannot evaluate from the lawn: the condition of the underlayment, the integrity of the decking, and whether attic ventilation is causing moisture to condense on the underside of the roof. A professional inspection also catches improper flashing details that look fine from below.
Photograph your roof from the same two or three angles every season and keep the images in a dated folder. When you file an insurance claim, a visual timeline of gradual wear versus sudden storm damage is one of the strongest pieces of evidence you can hand an adjuster.
How Homeowners Insurance Roof Coverage Ohio Works for Storm Damage
Homeowners insurance roof coverage in Ohio typically pays to repair or replace storm damage, but the policy language around cause, age, and depreciation decides how much you actually receive. Most Ohio policies cover sudden, accidental damage from wind, hail, and falling objects. They generally do not cover wear and tear, neglect, or gradual deterioration.
That distinction is where most claim disputes begin.
What Ohio Policies Typically Cover and Exclude
| Damage Type | Usually Covered | Usually Excluded |
|---|---|---|
| Wind lifting shingles | Yes | – |
| Hail bruising or punctures | Yes | – |
| Fallen tree limb impact | Yes | – |
| Gradual wear and aging | – | Yes |
| Neglected flashing leak | – | Yes |
| Ice damming (varies by policy) | Sometimes | Sometimes |
Two terms matter more than any other in your policy: actual cash value (ACV) and replacement cost value (RCV). An ACV policy pays today’s value minus depreciation, which on an older roof can be a fraction of the replacement price. An RCV policy pays the full replacement cost up to your limit. If your roof is more than fifteen years old, check which one you carry before a storm hits, not after.
For the official rules governing insurance in this state, homeowners can review Ohio Department of Insurance consumer resources. Filing deadlines and documentation requirements vary, so confirm the specifics of your own policy rather than relying on general guidance.
Never sign a roofing contract that promises to “handle everything with your insurance” before an adjuster has assessed the damage. Contracts that assign your claim rights to a contractor can leave you with less control and, in some cases, less money. Get the scope in writing first.
How to Choose a Reputable Roofer in Cincinnati
Choosing a reputable roofer in Cincinnati comes down to three verifiable things: a physical local address, proof of insurance, and a written scope of work before any money changes hands. Everything else is marketing.
Ask for these before you sign anything:
- A local business address you can drive past, not just a phone number
- Proof of general liability and workers’ compensation insurance
- Written references from customers who had storm damage claims, not just standard installs
- A detailed written estimate listing materials, quantities, and labor
- Warranty terms in writing, covering both materials and workmanship
A common mistake is choosing on price alone. The cheapest bid often omits ice-and-water shield, reuses existing flashing, or skips permit fees. Those shortcuts surface two years later as a leak you pay for twice.
What most guides miss is that the estimate itself tells you how the company operates. A one-line quote is a warning sign. A line-item scope that names the underlayment, the flashing detail, and the disposal plan is what a professional produces.
If you want a local team that has handled storm claims and complex historic roofs, DGK Home Solutions offers free assessments with no pressure and a written scope before work begins.
What Actually Drives Roof Repair Costs Up or Down
Roof repair costs are driven by four variables: the size and pitch of the roof, the material being replaced, the extent of hidden damage, and how quickly you act. Two houses on the same street can receive wildly different quotes for what sounds like the same repair.
Pitch is the underrated one. A steep roof requires more safety equipment, slower labor, and sometimes specialized crews (osha.gov). A flat or low-slope roof brings its own complications with drainage and membrane systems. Material matters too: replacing a section of architectural asphalt shingles is a different job than matching historic slate or clay tile.
Access is the fourth factor. A roof with mature trees crowding the eaves, or a home with limited driveway access for a dumpster, adds time and cost.
This is why honest estimates require an on-site evaluation. Anyone quoting a repair over the phone without seeing the roof is guessing, and you’ll be the one absorbing the difference when the crew finds rot under the shingles.
The single biggest lever on total roof repair costs isn’t the contractor you pick. It’s how early you address the problem. A repair caught in month one stays a repair. The same issue caught in year three becomes a replacement.
Preventative Maintenance That Keeps Small Fixes From Becoming Big Bills
Preventative maintenance is the cheapest insurance you’ll ever buy for your roof, and it costs far less than the repairs it prevents. A twice-yearly professional inspection, clean gutters, and prompt attention to small damage keep water out of the structure.
The routine that works:
- Clear gutters and downspouts in late spring and late fall, before and after leaf drop
- Trim overhanging branches so they don’t scrape shingles or drop debris
- Schedule a professional inspection every spring and after any major storm
- Address small repairs immediately, even when they seem cosmetic
- Keep a maintenance log with dates, photos, and receipts
That log does double duty. It protects your roof, and it strengthens any future insurance claim by documenting that you maintained the property responsibly.
If you’re in Liberty Twp and searching for a roofing company near me that actually answers the phone and follows through, DGK Home Solutions has built its reputation on prompt communication and honest assessments. Customers consistently mention that our crews explain what they find and why it matters, and that the process from estimate to cleanup was stress-free.
For homeowners preparing to sell, that same maintenance record becomes a selling point. A documented, well-maintained roof reassures buyers and can head off repair negotiations during inspection.
Roof problems are rarely sudden, even when the bill feels that way. Water finds the same weak points season after season, and the only real defense is catching them early. DGK Home Solutions brings over 20 years of experience to residential and commercial roofing, siding, and gutters across the Greater Cincinnati area, with honest assessments, clear communication, and full support through the insurance claim process. Get started with DGK Home Solutions and request your free quote today, so the next surprise on your roof is a good one.
Frequently Asked Questions
What are the most common hidden costs in roof repair?
The biggest hidden costs come from damage that is not visible until work begins, such as rotted decking, damaged flashing, or compromised underlayment. These are usually discovered once shingles are removed. Other surprises include code-required upgrades and unplanned gutter or soffit repairs. A thorough pre-work inspection and a written scope from your contractor are the best defenses against a bill that grows after the job starts.
Does homeowners insurance roof coverage Ohio policies include surprise roof repair costs?
Ohio homeowners insurance generally covers sudden damage from storms, hail, wind, or falling debris, but it does not cover wear and tear or neglect. That distinction matters: if a leak traces back to years of deferred maintenance, the claim may be denied. Review your policy’s dwelling coverage limits and deductible before storm season, and document your roof’s condition with photos so you can show what changed after an event.
How often should I have my roof inspected to avoid emergency repairs?
Schedule a professional inspection once a year and after any major storm. Homeowners can do simple visual checks each spring and fall from the ground. Catching a lifted shingle or a small flashing gap early usually means a minor repair instead of a full replacement. If your roof is over 15 years old, ask your inspector whether annual visits should become twice-yearly.
How can I tell if my roof repair estimate is accurate?
A trustworthy estimate is itemized, in writing, and specific about materials, labor, and timeline. It should list what is included, what is excluded, and how unexpected findings will be handled. Ask whether the price is fixed or subject to change, and request the contractor’s license and insurance information. If an estimate is vague or a contractor pressures you to sign the same day, get a second opinion before committing.