Table of Contents
- Public Adjuster vs Insurance Adjuster: Key Differences
- Understanding Public Adjuster Fee Percentage and Costs
- When to Hire a Public Adjuster for Your Claim
- The Insurance Claim Denial Process and Your Options
- Pros and Cons of Each Adjuster Type
- How to Choose the Right Representation for Your Claim
- Conclusion
Last Updated: August 15, 2026
Public Adjuster vs Insurance Adjuster: Key Differences
When property damage strikes, the question isn’t whether you need representation, it’s who should represent your interests. An insurance company adjuster works directly for the insurer to assess damage and determine payouts, they’re salaried employees incentivized to minimize costs and close claims quickly. A public adjuster works exclusively for you, the policyholder, earning a percentage of settlement increases they negotiate above the insurer’s initial offer.
This distinction shapes everything: how your claim gets evaluated, what documentation gets prioritized, how aggressively your case gets negotiated, and ultimately, how much money ends up in your pocket. The core tension is simple: insurance company adjusters and public adjusters have opposing financial incentives. Understanding that conflict is key to making an informed decision about which type of representation serves your situation best.
Understanding Public Adjuster Fee Percentage and Costs
Public adjusters operate on contingency fees, earning a percentage of the settlement increase they negotiate. However, the fee structure itself is far more negotiable than most homeowners realize.
Standard Fee Ranges and What Drives Them
Typical contingency fees range from 10% to 20% of the final settlement amount. State regulations often cap maximum fees, especially for disaster claims, but these caps vary significantly by jurisdiction. Some states cap public adjuster fees at 10% for all claims, while others allow up to 20% or higher depending on claim complexity. Before hiring, verify your state’s regulatory cap through your Department of Insurance.
Claim complexity matters: a straightforward water damage claim might settle at 10%, while a catastrophic multi-structure loss could reach 15-20%. Larger settlements sometimes carry lower percentage fees because the absolute dollar amount remains substantial.
The Math: When a Fee Actually Makes Sense
If an insurance company offers $50,000 and a public adjuster negotiates the settlement to $80,000, their fee is typically 10-20% of that $30,000 increase, meaning $3,000 to $6,000. You keep the remaining $24,000 to $27,000 in additional settlement. For smaller claims under $25,000, public adjusters may decline representation because the fee won’t justify their time investment. For mid-range claims ($50,000-$150,000), they’re often highly motivated. For catastrophic losses exceeding $500,000, public adjusters can recover hundreds of thousands in additional settlement, making their percentage fee negligible compared to absolute dollars gained.
Fee Negotiation: What Most Articles Don’t Tell You
Your fee percentage is negotiable, particularly for large or complex claims. Many homeowners don’t realize this because adjusters present their standard rate as non-negotiable. In reality:
- For claims exceeding $200,000, you have leverage to negotiate a lower percentage. An adjuster earning 12% on a $300,000 claim increase may accept 10% rather than lose the engagement.
- For claims with multiple properties or business interruption components, the fee percentage may be negotiable downward if you commit early and provide complete documentation.
- Flat-fee arrangements are rarer but worth exploring, especially for claims where the damage scope is well-defined.
Always ask: "Is this percentage negotiable?" Many adjusters will reduce their rate by 1-3 percentage points if asked directly.
Hidden Costs and Contract Terms to Watch
Before signing a fee agreement, clarify what’s included and what costs fall on you:
- Expert assessments: Confirm whether structural engineers, contractors, or forensic specialists’ costs come out of your settlement increase or are billed upfront. Reputable adjusters should absorb these costs as part of their contingency arrangement.
- Appraisal fees: If the claim goes to appraisal, who pays? Get this in writing.
- Appeal or litigation support: If your claim is denied and you pursue an appeal or bad faith claim, does the adjuster’s fee apply to additional recovery, or is there a separate arrangement?
- Fee caps: Some contracts specify a maximum fee regardless of settlement size, protecting you on very large claims.
Written Fee Agreement: Non-Negotiable
Before hiring a public adjuster, insist on a written fee agreement that specifies:
- The exact percentage fee and how it’s calculated
- Any state-mandated caps that apply
- Whether the fee is negotiable if the claim settles quickly or goes to appraisal
- What costs are included versus billed separately
- The timeline for fee payment (typically within 30 days of settlement)
- Conditions under which either party can terminate the agreement
If an adjuster refuses to provide a written fee agreement or resists clarifying these terms, that’s a red flag. Reputable adjusters welcome transparency.
State-Specific Fee Regulations
Fee caps and regulations vary by state. Before hiring, check your state’s Department of Insurance website for maximum allowable fee percentages, whether fees are capped differently for disaster claims, and licensing requirements for the adjuster you’re considering.
When to Hire a Public Adjuster for Your Claim
The decision hinges on three factors: claim complexity, the insurer’s initial offer, and whether you have the time and expertise to handle negotiations yourself.
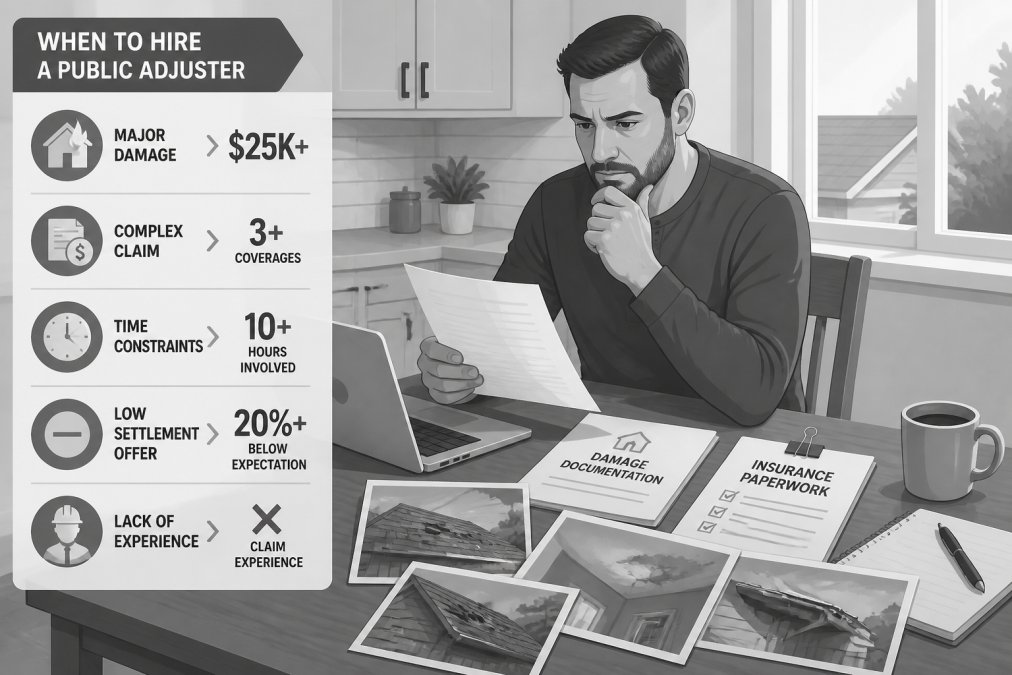
Hire a public adjuster if your claim involves multiple types of damage (roof, siding, water intrusion), structural issues, or business interruption components. Insurance company adjusters are trained to process claims efficiently, not to maximize payouts. They often miss secondary damage or fail to account for code-upgrade costs. A public adjuster specializes in finding money the initial estimate overlooked.
Consider a public adjuster if the insurer’s initial offer feels significantly low. If they offered $40,000 but your contractor estimates $70,000 in repairs, that gap suggests room for negotiation. The contingency fee structure means you only pay if they succeed in increasing the settlement.
Timing matters too. The earlier you hire a public adjuster, the better. They can guide documentation from the start, ensuring nothing gets missed. However, don’t hire a public adjuster for straightforward, low-value claims. If your roof needs $8,000 in repairs and the insurer offered $7,500, the adjuster’s fee might exceed the settlement increase they can negotiate.
The Insurance Claim Denial Process and Your Options
Understanding why claims get denied, and what you can do about it, is critical to knowing whether a public adjuster becomes necessary, or whether you need an attorney instead.
Why Claims Get Denied: Legitimate vs. Aggressive Interpretations
Insurance companies deny claims for several reasons:
- Coverage exclusions: The damage isn’t covered under your specific policy (e.g., flood damage without flood insurance).
- Policy conditions not met: You failed to maintain the property or didn’t report damage within the required timeframe.
- Excluded perils: The damage resulted from a cause explicitly excluded in your policy (e.g., wear and tear).
- Pre-existing damage: The insurer claims the damage predates your policy or was caused by a prior event.
Some denials are legitimate. Others are aggressive interpretations of policy language designed to avoid payout. The difference matters because it determines your next move.
Step 1: Request a Detailed Written Explanation
When a claim gets denied, request a detailed written explanation of why. Insurance carriers must provide this under state law (typically within 30 days). The explanation must cite the specific policy language and the factual basis for the denial. Review this explanation carefully against your actual policy. Many denials rest on misinterpretations of what your policy covers.
Step 2: File a Formal Appeal with Documentation
If you believe the denial is wrong, file a formal appeal. A public adjuster becomes valuable here. They understand policy language deeply and can reframe your claim with stronger documentation and expert interpretation. They’ll gather evidence contradicting the denial, cite policy language supporting your coverage, prepare a detailed written response, and negotiate directly with the insurer’s claims manager.
Step 3: Understand Bad Faith vs. Simple Denial
A claim denial is a business decision by the insurer. You disagree, and you appeal. This is normal.
Bad faith is different. It occurs when an insurer denies a claim they know is valid without reasonable basis, fails to conduct a reasonable investigation, misrepresents policy language, ignores supporting evidence, deliberately delays processing, or retaliates against you for hiring an adjuster. Bad faith is a legal violation that can result in damages far exceeding your original claim amount, including attorney fees and punitive damages.
When You Need a Public Adjuster vs. When You Need an Attorney
Hire a public adjuster if:
- Your claim was denied but the policy language supports your coverage
- You need expert damage assessment and documentation to challenge the denial
- You want to negotiate a reversal without litigation
Hire an attorney if:
- You believe the denial is in bad faith (the insurer is acting unreasonably or deceptively)
- The insurer has a pattern of denying valid claims
- You’ve appealed and the insurer still refuses to pay a claim you believe is clearly valid
- The claim amount is large enough to justify legal fees (typically $50,000+)
- You need to file a lawsuit or pursue bad faith litigation
The Timeline Matters: When to Act
Most states have strict deadlines for filing bad faith claims or lawsuits. If you wait too long after a denial, you may lose your right to sue. Typical timelines are 2-4 years from the date of the denial, though some states have shorter windows. If you suspect bad faith, consult an attorney within 6 months of the denial.
Red Flags That Suggest Bad Faith
If any of these occur, bad faith may be at play: the insurer denies your claim without conducting a thorough investigation, denies coverage based on policy language that doesn’t actually exclude your damage, ignores expert reports or evidence you’ve provided, delays processing for months without explanation, pressures you to accept a settlement far below your contractor’s estimate, retaliates after you hire a public adjuster, or misrepresents what your policy covers.
Building Your Case: Public Adjuster + Attorney Strategy
For complex claims where bad faith is possible, the strongest approach is: hire a public adjuster immediately to document damage and prepare a detailed appeal, consult an attorney to evaluate whether bad faith is present, let the adjuster handle the appeal while the attorney monitors for bad faith indicators, and if the appeal fails, the attorney can pursue bad faith litigation while the adjuster’s documentation supports your case.
Pros and Cons of Each Adjuster Type
Insurance Company Adjusters
Pros: They’re free to you. They’re regulated and licensed, ensuring minimum competency standards. The process moves quickly because they’re motivated to close claims efficiently.
Cons: Their financial incentive is to minimize payout, not maximize your recovery. They work for the insurance company, not you. They may lack expertise in complex damage assessment or overlook secondary damage. For contentious claims, their recommendations often favor the insurer’s position.
Public Adjusters
Pros: They work exclusively for you, with no conflict of interest. They have strong incentives to find every dollar of additional settlement. They bring specialized expertise in damage assessment, policy interpretation, and negotiation. They handle all documentation and communication, reducing stress on you. For complex or high-value claims, they often recover far more than their fee costs.
Cons: Their fee, 10-20% of settlement increase, can be substantial on large claims. They may not be cost-effective for small or straightforward claims. You’re dependent on their competence and honesty.
How to Choose the Right Representation for Your Claim
Start by assessing your claim’s complexity and size. If it’s straightforward and under $25,000, you likely don’t need a public adjuster. For complex claims or those exceeding $50,000, interview 2-3 public adjusters. Ask about their experience with your specific type of damage and request references from past clients with similar claims. Verify their licensing through your state’s Department of Insurance.
Ask each adjuster for a written fee agreement before hiring. Understand exactly how they calculate their percentage, whether there are caps, and what services are included. Evaluate whether you have the time and expertise to negotiate with the insurer yourself. If you work full-time, managing a complex claim is genuinely difficult. Adjusters handle all communication, documentation, and negotiation, a significant value even before considering settlement increases.
Consider your insurer’s reputation. If they have a history of denying valid claims or dragging out settlements, a public adjuster’s advocacy becomes more valuable. Finally, don’t wait. The sooner you hire representation, the better your documentation. Act within days of discovering damage, not weeks.
Conclusion
Choosing between a public adjuster and relying on an insurance company adjuster depends on your claim’s complexity, size, and your own capacity to manage the process. For straightforward claims under $25,000, the insurer’s adjuster often suffices. For complex or high-value claims, a public adjuster’s expertise and aligned incentives frequently recover enough additional settlement to justify their contingency fee.
The real advantage of a public adjuster isn’t just the money they recover, it’s the stress relief and professional advocacy. When property damage disrupts your life, having someone who works exclusively in your interest, managing documentation and negotiation while you focus on repairs and recovery, has genuine value.
At DGK Home Solutions, we’ve guided homeowners through this decision for over 20 years. Whether you need help assessing damage, understanding your policy, or deciding if a public adjuster makes financial sense, our team is here to provide honest guidance. Contact DGK Home Solutions today for a free consultation that helps you make the right choice for your specific circumstances.
Frequently Asked Questions
What is the downside of using a public adjuster?
Public adjusters charge contingency fees ranging from 10-20% of your final settlement, which can significantly reduce your payout. They may also extend the claims process timeline. For small or straightforward claims, the fee can outweigh the benefit. Additionally, not all states regulate public adjusters equally, so licensing and oversight varies. You'll want to verify their credentials and understand the contractual obligations before signing.
When is the best time to hire a public adjuster?
Hire a public adjuster early in the claims process if your initial settlement offer seems substantially lower than your actual losses, or if you're facing a denied claim. The best timing is after you've received the insurance company's initial assessment but before you accept any settlement offer. Acting quickly ensures the public adjuster can participate in the full claim investigation and negotiate from the start, maximizing your claim recovery.
Do public adjusters actually get higher settlements?
Yes, public adjusters often secure significantly higher settlements than initial insurance company offers. Many cases show settlements 40-700% above the insurer's first proposal, depending on claim complexity and the extent of underpayment. However, results vary based on the specific damage, your policy limits, and the adjuster's expertise. The contingency fee structure aligns their incentive with yours, they only profit when you receive a larger payout.
Is it wise to hire a public adjuster for a small claim?
For small claims, a public adjuster may not be cost-effective. If your claim is under $5,000-$10,000, the 10-20% contingency fee could consume most of your recovery. Instead, consider handling a straightforward small claim directly with your insurance company or consulting a contractor who offers insurance claim assistance. Reserve public adjusters for substantial claims where their expertise and negotiation skills justify the fee.
This article was written using GrandRanker