Table of Contents
- Understanding Eligibility for Old Siding Damage Claims
- How to Document Storm Damage to Siding
- Siding Matching Laws and Ohio Insurance Requirements
- How to File a Home Insurance Claim for Siding
- Common Challenges When Filing for Old Siding Damage
- Getting Professional Help With Your Claim
- Frequently Asked Questions
Last Updated: September 2, 2026
Understanding Eligibility for Old Siding Damage Claims
Whether you can file a claim for old siding damage depends on what caused the damage, not how old your siding is. Insurance companies distinguish between deterioration from wear and tear, which they won’t cover, and sudden, accidental damage from a covered peril like a storm, which they will. A 20-year-old siding panel torn open by a fallen tree branch during a windstorm qualifies for coverage; the same panel simply faded and weathered does not. The age of the material is irrelevant. What matters is the cause.
At DGK Home Solutions, we work with homeowners throughout the Greater Cincinnati area who face exactly this situation. We’ve helped dozens of clients navigate the claims process for storm damage to older homes, and the pattern is clear: most people don’t realize they have a legitimate claim because they focus on the age of their siding instead of the event that damaged it.
Age vs. Cause: What Your Insurance Actually Covers
Your homeowner’s insurance policy covers sudden, accidental damage from specific causes called “covered perils,” typically including windstorms, hail, lightning, and falling objects (iii.org). What your policy does NOT cover is gradual deterioration, normal wear and tear, or damage from lack of maintenance.
The age of your siding doesn’t automatically disqualify a claim. A 25-year-old siding panel damaged by a severe storm is still eligible for coverage. What can disqualify you is if the adjuster determines the damage resulted from poor maintenance or existing deterioration rather than the storm event itself. Documentation is critical: photos showing your siding was in good condition before a storm and new damage immediately after create a strong claim. If your siding was already cracked and failing before the storm, the adjuster may argue the storm merely exposed existing problems.
The Difference Between Wear and Tear and Storm Damage
Wear and tear develops gradually over years, fading from sun exposure, peeling paint, and failing seams from dried caulk. These are maintenance issues, not insurable events. Storm damage is different: a windstorm rips vinyl panels off, hail punches holes through fiber cement, or a falling branch tears a section clean away. These sudden, accidental events happen in minutes, not months.
The challenge arises when your siding has existing damage and then a storm hits. The adjuster must determine what portion is storm-related and what portion was pre-existing. Photographic evidence before the storm becomes invaluable in these situations.
How to Document Storm Damage to Siding
Documentation is your strongest tool when filing a claim for old siding damage. Adjusters make decisions based on evidence.
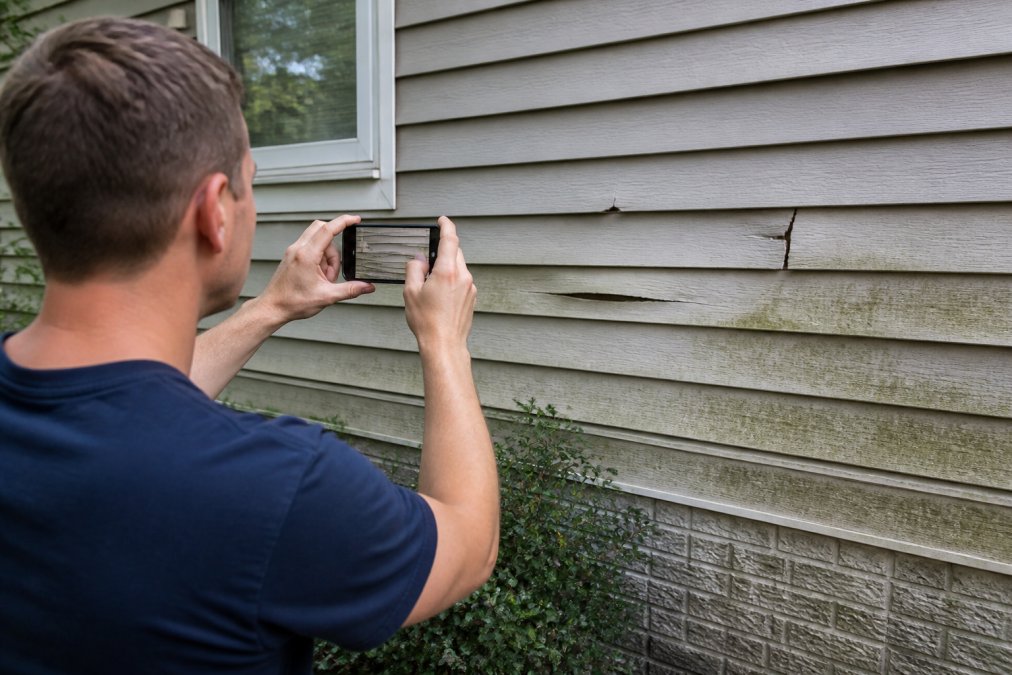
What to Photograph and When
Photograph damage as soon as it’s safe to do so, within 24-48 hours while damage is fresh. Use daylight with good natural lighting for clear details. Take wide shots showing the full extent of affected areas, then close-ups of specific damage: torn seams, missing panels, impact marks, cracks, and separation from trim. Include a reference object like a coin or ruler to show scale. Photograph surrounding undamaged siding for comparison, establishing that your siding was intact before the storm. If possible, document the weather event itself, fallen branches, debris, or hail damage to other surfaces, to corroborate your account.
Gathering Supporting Evidence
Collect written records related to the storm: news articles about severe weather, National Weather Service reports, or local emergency management announcements. These prove a significant weather event occurred on the date you claim damage happened.
If you had your siding inspected recently, gather those records. An inspection report from before the storm showing your siding was in good condition is powerful evidence. Gather repair estimates from contractors describing the damage in detail and specifying storm impact rather than wear and tear. Collect any communication with neighbors about the storm; if multiple people sustained similar damage, written statements strengthen your claim.
Siding Matching Laws and Ohio Insurance Requirements
When your siding is damaged and needs replacement, new siding won’t match the old. Older styles, colors, and materials are often discontinued. Installing new matching siding across your entire wall looks better than patching but costs significantly more.
Ohio law allows insurers to apply depreciation to claims for property damage, reducing the payout based on age and condition. A 15-year-old siding panel costing $200 new might be valued at $100 after depreciation. However, many homeowner’s policies include a “replacement cost” endorsement that eliminates or reduces depreciation for certain types of damage. Review your policy documents carefully to determine whether your coverage includes replacement cost protection.
Ohio does not have a statewide siding matching law, but individual insurers may offer coverage addressing this issue. Contact your insurer directly to ask whether your policy covers matching costs for storm damage to siding.
How to File a Home Insurance Claim for Siding
Filing a claim for old siding damage follows a straightforward process, but timing and documentation matter.
Step 1: Contact Your Insurance Company Immediately
Call your insurance agent or the claims number on your policy within 24 hours of discovering damage. Describe the damage briefly and explain the cause. Provide your policy number and the date you discovered the damage. Ask for a claim number and the name of your assigned adjuster. Ask when the adjuster will contact you to schedule an inspection.
Step 2: Submit Your Documentation and Evidence
Compile all your photos, weather reports, contractor estimates, and supporting documents before the adjuster arrives. Organize them in a folder for easy reference. During the inspection, walk the adjuster through your documentation, showing before-and-after photos and pointing out the damage pattern. Be honest and straightforward; adjusters spot inflated claims quickly. After the inspection, submit any additional documentation the adjuster requests promptly.
Step 3: Work With the Insurance Adjuster
The adjuster’s role is to determine what damage is covered under your policy and estimate repair costs. If the adjuster’s estimate seems low, obtain your own estimate from a contractor and submit it for comparison. Many policies include an appraisal clause allowing you to request an independent appraisal if you disagree with the adjuster’s estimate. If the adjuster denies your claim or offers an unfair settlement, ask for a written explanation and review your policy language. Contact your state’s Department of Insurance for guidance if you believe they’ve misinterpreted your coverage.
Common Challenges When Filing for Old Siding Damage
Most claims for old siding damage encounter at least one obstacle.
Denial Due to Age or Depreciation
The most common challenge is the adjuster arguing that your siding’s age disqualifies the claim or that depreciation reduces the payout significantly. This happens because adjusters apply “actual cash value” (ACV) rather than “replacement cost value” (RCV).
Under ACV, the insurer pays replacement cost minus depreciation. A 20-year-old siding panel might have a replacement cost of $300 but an ACV of only $50 (peer-reviewed research). Under RCV, you receive full replacement cost without depreciation. Review your policy documents for replacement cost coverage language. If your policy includes replacement cost protection, provide that section to the adjuster in writing. Some policies allow you to upgrade coverage to RCV for specific perils like windstorms.
Proof of Storm Causation
Adjusters sometimes deny claims by arguing the damage resulted from pre-existing deterioration rather than the storm. Counter this by providing clear before-and-after evidence. If you lack pre-storm photos, gather statements from neighbors or contractors testifying your siding was in good condition before the storm. Weather documentation also helps, show that a significant storm occurred on the date you claim damage happened.
Settlement Disputes and Appeals
When the adjuster’s settlement offer is lower than your estimate, request a detailed written explanation of their calculation. Obtain a second estimate from another contractor and submit it for comparison. If you can’t reach agreement, invoke the appraisal clause if available. If the adjuster denies your claim and you believe the denial is wrong, file a complaint with Ohio’s Department of Insurance.
Getting Professional Help With Your Claim
Navigating an insurance claim for old siding damage is manageable on your own, but professional help can significantly improve your outcome.
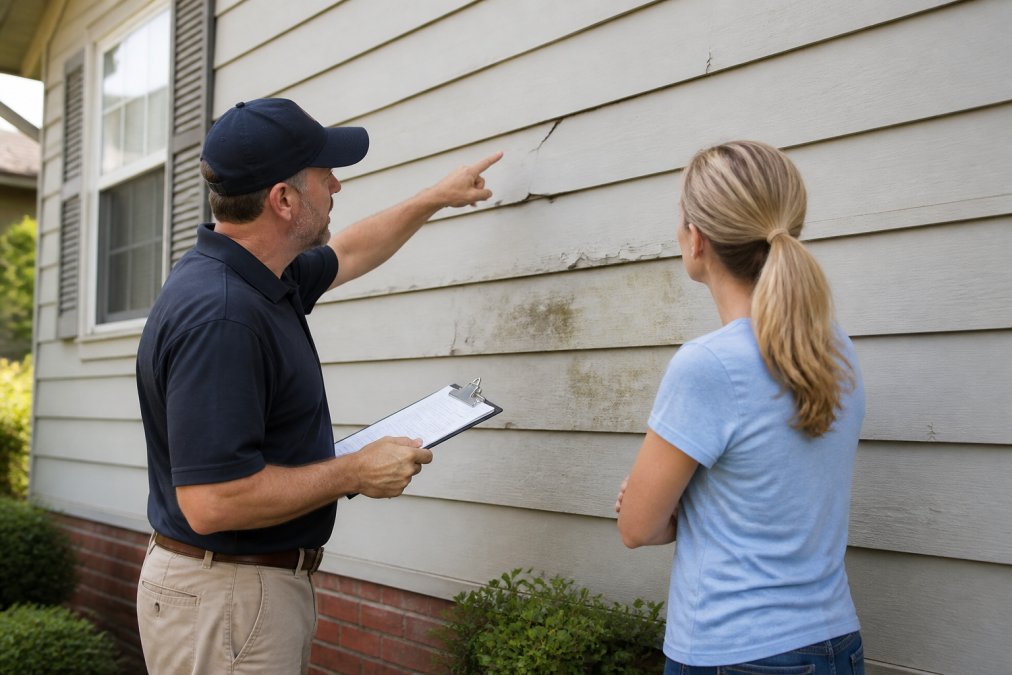
A public adjuster is a licensed professional who represents you in your claim, charging a percentage of the settlement obtained, typically 10 percent (ohio.gov). They often recover far more than that percentage costs. A contractor specializing in insurance claims understands what adjusters look for in documentation and estimates. An insurance attorney becomes necessary if your claim is denied and you want to pursue legal action. Many homeowners hesitate to hire professionals due to cost, but if your claim is for several thousand dollars, professional fees often result in a larger settlement that more than covers the cost.
Filing a claim for old siding damage is absolutely possible when the damage results from a covered storm event rather than wear and tear. The key is documenting the damage thoroughly, understanding your policy coverage, and working with professionals who can strengthen your claim. When you’re ready to address the damage itself, DGK Home Solutions provides expert siding repair and replacement throughout the Greater Cincinnati area. Our team has over 20 years of experience helping homeowners navigate insurance claims and restore their homes to full condition. Contact us for a free assessment of your siding damage and guidance on your claim.
Frequently Asked Questions
Does homeowners insurance cover wear and tear on siding?
No. Homeowners insurance covers damage from specific events like storms, hail, or falling debris, not gradual wear and tear from age or weather exposure. If your siding is damaged because it’s simply old, your claim will likely be denied. However, if a storm event caused damage to older siding, you may have a valid claim even if the siding was nearing the end of its life. The key is proving the damage was caused by a specific incident, not just deterioration over time.
How do I prove siding damage was caused by a storm?
Document the damage with detailed photographs and video taken immediately after the storm. Capture the damage location, severity, and any visible impact marks. Keep weather reports showing the storm occurred in your area, and note the storm date. If possible, get a statement from neighbors about the storm. When the insurance adjuster inspects, point out the damage pattern and explain how the storm caused it. Professional inspections from contractors can also support your claim by confirming the damage type and cause.
Will insurance pay for matching siding on all sides of my house?
It depends on your policy and the extent of damage. If only one section of siding is damaged, insurance typically covers repair or replacement of that section only. However, if matching siding is no longer available and replacement requires updating the entire side or house, your policy may cover the cost difference. Ohio insurance requirements vary by policy. Review your homeowners insurance policy or contact your agent to understand matching coverage. This is especially important for older homes where original siding materials may be discontinued.
What is the statute of limitations for filing a property damage claim in Ohio?
In Ohio, you generally have four years from the date of loss to file a property damage claim. However, don’t wait that long, file as soon as possible after discovering damage. Insurance companies expect prompt notification, and delays can complicate your claim or lead to denial. Document damage immediately and contact your insurer within days of discovering the problem. Waiting weeks or months makes it harder to prove the damage was recent and caused by a covered event.
This article was written using GrandRanker