Table of Contents
- What Commercial Insurance Typically Covers on Roofs
- Maintenance vs. Damage: The Critical Distinction
- Commercial Roof Preventative Maintenance Checklist
- Common Exclusions and Limitations in Commercial Policies
- How to File a Commercial Roof Insurance Claim in Ohio
- Steps to Ensure Your Roof Coverage Is Adequate
- Conclusion
Last Updated: August 28, 2026
What Commercial Insurance Typically Covers on Roofs
Commercial insurance policies cover sudden, accidental damage to roofs, such as storm damage, hail, or falling objects, rather than routine upkeep. The key distinction is that insurance protects against unexpected events, not wear-and-tear over time.
Does commercial insurance cover roof maintenance? No. Insurance companies distinguish between damage (covered) and maintenance (not covered). Most commercial policies cover weather damage, falling objects, and structural collapse, but only if your roof was in reasonable condition when damage occurred. If poor maintenance contributed to the damage, your claim could be denied or reduced.
At DGK Home Solutions, we’ve worked with commercial property owners navigating these distinctions. The most common misunderstanding is assuming that any damage will be covered. In reality, insurers investigate whether negligence or deferred maintenance played a role. A roof that hasn’t been inspected in years may face scrutiny if a leak develops during a storm.
Regular roof inspections create a documented maintenance history. If a claim is filed, this record shows you’ve been responsible stewards of the property, strengthening your position with the insurer.
Maintenance vs. Damage: The Critical Distinction
Understanding the difference between maintenance and damage determines what your commercial insurance will and won’t pay for.
Maintenance includes routine tasks designed to keep the roof in good working order: clearing debris, inspecting for wear, resealing flashings, patching minor cracks, and replacing damaged shingles before they leak. Insurance companies do not cover maintenance because it’s your responsibility as the property owner.
Damage is sudden and unforeseeable: a hailstorm punches holes in the roof, wind rips off shingles, or a tree limb crashes through the structure. These events happen to a properly maintained roof and are outside your control. Insurance covers damage.
The problem arises when deferred maintenance becomes damage. A small leak ignored for months can lead to structural rot. A clogged drain system can cause ponding water that deteriorates the membrane. When the insurer investigates, they’ll ask whether routine maintenance would have prevented the damage. If yes, they may deny the claim.
The National Roofing Contractors Association guidelines recommend inspections at least twice per year for commercial properties, particularly after severe weather. This is the standard that insurers expect. If your roof hasn’t been inspected in years and a claim is filed, the insurer will likely point to that gap as evidence of negligence.
If you’ve had a roof inspected, identified issues, and documented that you’re addressing them, you’re building a case for coverage. If you’ve ignored known problems, you’re building a case for denial. Insurance adjusters review maintenance records during claims investigations.
Maintenance is your obligation. Damage is the insurer’s obligation. The line between them is drawn by what a reasonable property owner would have done to prevent the problem.
Commercial Roof Preventative Maintenance Checklist
A systematic approach to roof maintenance protects your investment and strengthens your insurance position.
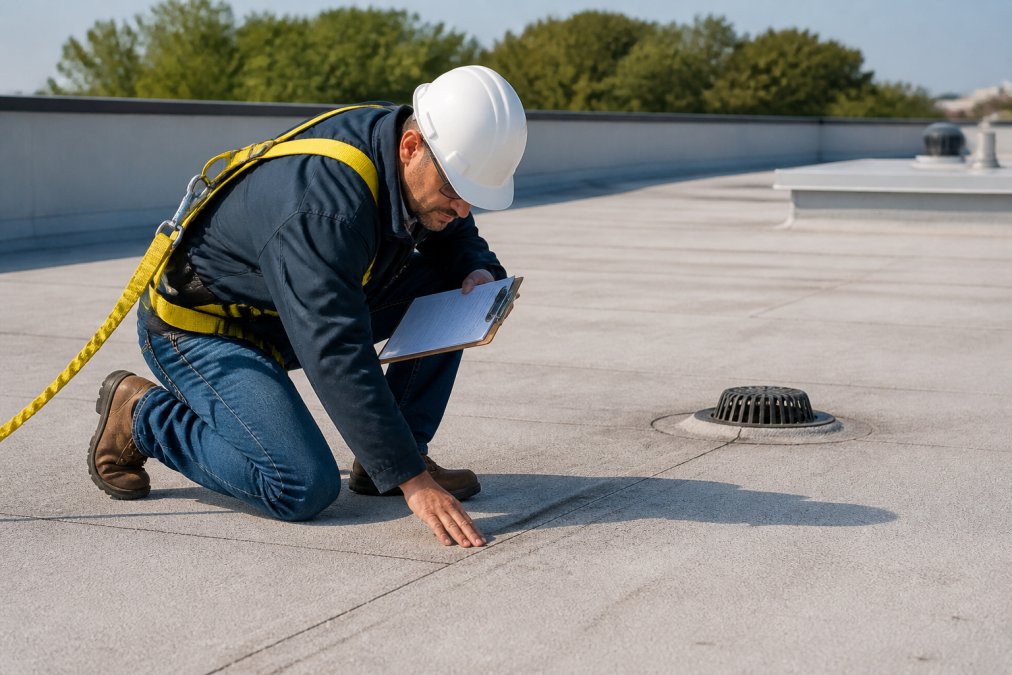
Conduct visual inspections at least twice per year, ideally in spring after winter weather and in fall before the season changes. Look for visible damage: cracks, blistering, punctures, missing or lifted shingles, and pooling water. Document what you see with photos and notes.
Check all penetrations where pipes, vents, and equipment pass through the roof. Flashings should be sealed and in good condition. Inspect the perimeter where the roof meets walls or parapets, as water often finds its way in at these transitions.
Clear debris regularly. Leaves, branches, and dirt trap moisture and accelerate deterioration. Ensure gutters and downspouts drain properly. Standing water on a flat roof indicates a drainage issue that needs fixing.
Inspect sealants and caulk around all roof penetrations and seams. Over time, these materials shrink and crack. Resealing is inexpensive maintenance that prevents costly damage.
Document everything. Take photos of the roof’s condition, note any repairs or maintenance performed, and keep receipts. This documentation is invaluable if a claim is filed.
| Maintenance Task | Frequency | Priority | Documentation |
|---|---|---|---|
| Visual roof inspection | 2 times per year | High | Photos, notes, date |
| Clear debris and gutters | Spring and fall | High | Maintenance log |
| Check penetration seals | 2 times per year | High | Photos of condition |
| Inspect flashing condition | 2 times per year | High | Notes on wear |
| Reseal cracks or gaps | As needed | Medium | Receipts and photos |
| Check drainage systems | After heavy rain | High | Inspection notes |
Common Exclusions and Limitations in Commercial Policies
Commercial insurance policies contain exclusions and limitations that significantly affect coverage.
Most policies exclude damage from lack of maintenance. If an inspector determines that regular maintenance would have prevented the damage, coverage may be denied. Age-related wear is typically excluded. Most commercial roofs have a 15-20 year life expectancy (nrca.net). Some policies include a "roof age limit" and won’t cover roofs older than 20 or 25 years, even for sudden damage.
Gradual leaks are often excluded. Only sudden leaks from a specific event are covered. Pre-existing conditions are also excluded. Insurers require roof inspections before issuing or renewing policies to document the roof’s condition at the time coverage begins.
Weather-related exclusions vary. Most policies cover hail and wind damage, but some exclude certain types of weather or require high deductibles for wind damage. Flood damage is typically excluded from standard commercial policies.
Deductibles can be substantial. Commercial policies often have deductibles of 1-5% of the building’s insured value. Understanding your deductible is essential before filing a claim.
If your roof is [over 20 years](/roofing-service/) old, check your policy’s age limitations immediately. Many insurers won’t cover roofs beyond a certain age, regardless of condition. You may need to replace the roof to maintain coverage.
How to File a Commercial Roof Insurance Claim in Ohio
Filing a claim requires documentation, timing, and clear communication with your insurer.
Document the damage immediately. Take photos and videos of the affected area from multiple angles. Capture the damage in context, then zoom in on specific damage. If weather caused the damage, note the date and conditions.
Contact your insurance agent or broker as soon as possible. Most policies require prompt notification of damage. Your agent will guide you through the next steps and explain what the insurer needs.
The insurer will assign an adjuster to investigate the claim. Be prepared to provide access to the roof for inspection. The adjuster will look for signs of maintenance or neglect that might affect coverage.
Prepare a detailed claim statement including the date damage occurred, how you discovered it, what caused it, and a description of the damage. Provide your documentation, photos, videos, maintenance records, and contractor estimates.
Get repair estimates from qualified contractors. In the Liberty Twp area and throughout Ohio, contractors like DGK Home Solutions can provide detailed estimates that document the scope of damage and repair costs.
Be transparent about maintenance history. If you have records showing regular inspections and maintenance, provide them. This demonstrates that damage wasn’t caused by negligence.
Understand the claims process timeline. In Ohio, insurers must acknowledge receipt of a claim within a few business days and typically have 30 days to investigate and make a decision (ohio.gov).
Keep a separate file for all roof-related documents: inspections, maintenance records, repair estimates, and communications with your insurer. When a claim is filed, you’ll have everything organized and ready to submit.
Steps to Ensure Your Roof Coverage Is Adequate
Start with a professional roof inspection before renewing your policy. Many insurers require this for commercial properties. An inspection identifies existing damage, documents the roof’s condition, and helps you understand what maintenance is needed.
Review your policy annually. Insurance needs change as your property changes. If your roof is aging, address age-related limitations before they become a problem.
Maintain detailed records of all roof maintenance and repairs. Keep receipts, invoices, and photos. These records prove you’ve been responsible stewards of the property and strengthen your position if a claim is filed.
Communicate with your insurance agent about roof condition. If you’re aware of issues or planning major repairs, inform your agent. This open communication prevents surprises and ensures your coverage remains appropriate.
Consider roof maintenance contracts with qualified contractors. Regular professional inspections and maintenance provide expertise and create documentation for your insurer. DGK Home Solutions, serving the Greater Cincinnati area, can establish a maintenance schedule that keeps your roof in good condition.
Address maintenance issues promptly. Small problems become large ones. When you defer maintenance and damage occurs, insurers are more likely to deny claims.
Review your deductible. A higher deductible lowers your premium but means you pay more out of pocket if a claim is filed. Choose a deductible that aligns with your financial situation.
Insurance is a partnership between you and your insurer. You maintain the property responsibly. They cover unexpected damage. When both parties fulfill their obligations, claims are paid and properties are protected.
Conclusion
Does commercial insurance cover roof maintenance? No, but it does cover damage that occurs to a properly maintained roof. Insurance covers sudden, accidental damage like hail, wind, and falling objects. It does not cover routine maintenance, gradual deterioration, or damage caused by deferred upkeep.
The path to reliable coverage is straightforward: maintain your roof properly, document that maintenance, and understand your policy’s terms and limitations. Inspect your roof regularly, clear debris, reseal penetrations, address problems promptly, and keep records.
For commercial property owners in Ohio and the Greater Cincinnati area, professional roof maintenance and inspection services are essential. DGK Home Solutions brings over 20 years of experience in commercial roofing and can help establish a maintenance program that keeps your roof protected and your insurance claims-ready. Our team provides honest assessments of your roof’s condition, clear communication about what’s needed, and professional repairs that meet insurance standards.
When you need a roof inspection, maintenance plan, or help navigating an insurance claim, DGK Home Solutions is ready to assist. Contact us for a free quote and let our experience protect your property.
Frequently Asked Questions
Q: Does commercial property insurance cover roof repairs from storm damage?
A: Yes, most commercial insurance policies cover roof repairs caused by sudden, unexpected events like hail, wind, or falling tree limbs. However, the coverage depends on your specific policy terms and the cause of the damage. Gradual wear, poor maintenance, or pre-existing conditions are typically not covered. Review your policy's declarations page or contact your insurance agent to confirm what events trigger roof repair coverage.
Q: What is the difference between roof maintenance and roof damage for insurance purposes?
A: Maintenance includes routine upkeep like cleaning gutters, removing debris, and inspecting for leaks, activities that prevent problems. Insurance does not cover maintenance costs. Damage is sudden, accidental harm from storms, fire, or falling objects. Insurance covers damage repairs. If your roof fails because you neglected maintenance, insurers may deny a damage claim, arguing the failure resulted from lack of care rather than a covered event.
Q: What should I document when filing a commercial roof insurance claim in Ohio?
A: Document the date and time of the damage, take clear photos and videos of affected areas from multiple angles, keep receipts for emergency repairs, and gather witness statements if available. Note weather conditions on the damage date. Obtain a professional roof inspection report. Keep copies of your insurance policy and any previous maintenance records. Submit all documentation promptly to your insurer with a detailed written description of what happened and the damage extent.
Q: Does commercial insurance cover wear and tear on a roof?
A: No. Wear and tear, gradual deterioration from age, weather exposure, and normal use, is explicitly excluded from commercial insurance policies. Insurers expect property owners to maintain roofs through regular preventative care. If your roof fails due to age or neglect, the claim will likely be denied. This is why maintaining a commercial roof preventative maintenance checklist and documenting regular inspections is critical for protecting both your property and your coverage.
Get a FREE QUOTE from DGK Home Solutions today. Our team will inspect your commercial roof, assess its condition, document maintenance needs, and help ensure your insurance coverage is adequate. With over 20 years of experience serving commercial property owners throughout Ohio and Indiana, we deliver the professional service and honest guidance your property deserves.
This article was written using GrandRanker