Table of Contents
- Mistake 1: Waiting Too Long to File Your Claim
- Mistake 2: Failing to Document Storm Damage for Insurance Properly
- Mistake 3: Not Taking Immediate Safety Steps After Storm Damage
- Mistake 4: Hiring Unlicensed or Uninsured Contractors
- Mistake 5: Accepting the First Insurance Estimate Without Question
- How to Handle Roof Insurance Claims: The Right Approach
- Understanding the Ohio Storm Damage Claim Timeline
- Mistake 6: Making Repairs Before the Adjuster Inspects
Last Updated: August 29, 2026
When a storm damages your home in the Greater Cincinnati area, navigating the insurance claim process correctly is essential. Many homeowners make costly mistakes during this critical window, from waiting too long to file to accepting lowball estimates without question. At DGK Home Solutions, we’ve helped countless property owners in Liberty Twp and surrounding areas recover from storm damage. This guide covers the 10 most common storm damage insurance claim mistakes and how to avoid them, ensuring you get the full coverage you deserve.
Mistake 1: Waiting Too Long to File Your Claim
Most insurance policies require you to report damage within 30 to 90 days, depending on your policy terms (naic.org). The longer you wait, the harder it becomes to prove the damage was caused by the storm and not by pre-existing conditions or neglect. Evidence deteriorates, photos fade in quality, contractors’ schedules fill up, and water damage spreads, potentially causing mold that your insurer may not cover if you didn’t mitigate promptly.
Contact your insurance company immediately when storm damage occurs. Don’t wait for a contractor to assess the damage first, your insurer needs to know right away. This protects your claim and sets the timeline for everything that follows.
Mistake 2: Failing to Document Storm Damage for Insurance Properly
Documentation is the backbone of your claim. Without clear, detailed records, you’re asking your insurance adjuster to take your word for the extent and cost of damage.
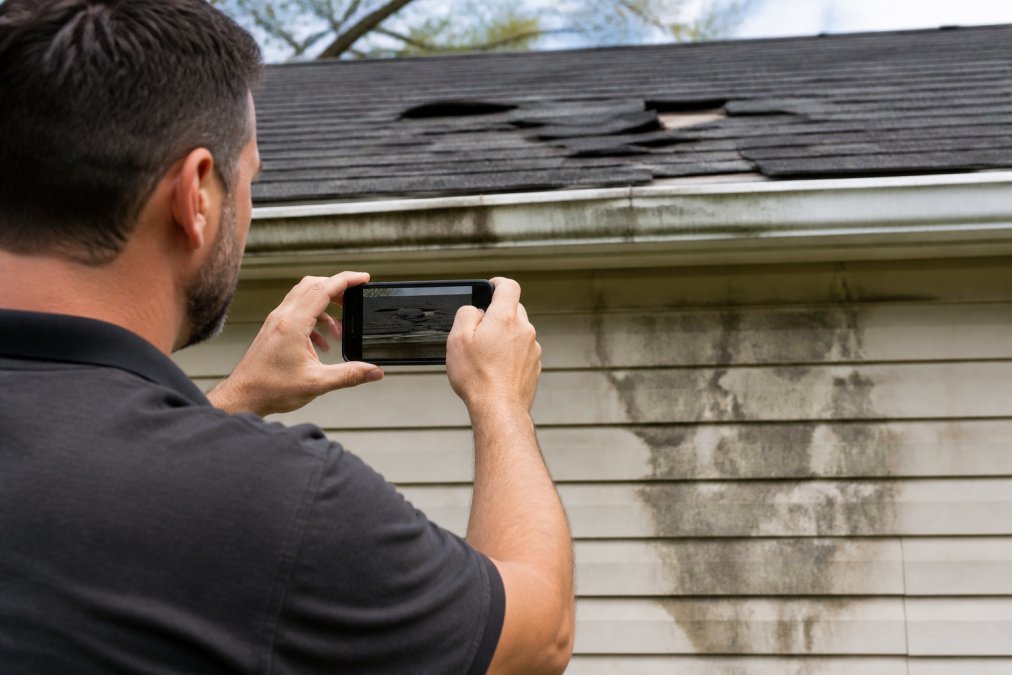
Photograph every damaged area from multiple angles and distances. Capture wide shots showing overall scope, then zoom in on specific damage points. Document water stains, broken windows, missing shingles, gutter damage, and debris. Write detailed notes alongside your photos: the date taken, location, and description of damage.
Use the free NAIC Home Inventory App to organize documentation by room and category, making it easy to share with your adjuster. Keep receipts for any temporary repairs you make to prevent further damage, these mitigation costs are typically covered by insurance.
Mistake 3: Not Taking Immediate Safety Steps After Storm Damage
After a storm, your property may have exposed wiring, unstable structures, or hazardous debris. Make your property safe first. Your insurance policy requires you to take reasonable steps to prevent further damage, known as mitigation. Failure to mitigate can result in claim denials or reduced payouts.
Document your mitigation efforts with photos, receipts, and dates. When the adjuster arrives, point out the temporary measures you’ve taken. This demonstrates that you’re protecting the property and taking the claim seriously.
Mistake 4: Hiring Unlicensed or Uninsured Contractors
Hiring an unlicensed or uninsured contractor can invalidate your claim. If an unlicensed contractor causes additional damage, you have no recourse. If someone is injured on your property, you could be held liable. If your insurance company discovers you hired an unlicensed contractor for claim-related work, they may deny coverage.
Before hiring anyone, verify their licensing. In Ohio, roofing contractors must be licensed, check against the Ohio Construction Industry Licensing Board records (com.ohio.gov). Verify that the contractor carries liability insurance and workers’ compensation insurance. Ask for certificates of insurance and confirm they’re current. Get multiple bids from licensed contractors.
DGK Home Solutions, serving Liberty Twp and the Greater Cincinnati area for over 20 years, maintains full licensing and insurance on all residential and commercial roofing, siding, and gutter work.
Mistake 5: Accepting the First Insurance Estimate Without Question
Your insurance company’s estimate is not the final word. Insurance estimates are often conservative, designed to minimize the insurer’s payout. You have the right to dispute it by hiring your own contractor to prepare an independent estimate, called a "scope of work" or "repair estimate."
Common areas where adjusters underestimate include roof replacement costs, hidden water damage, and structural repairs. An adjuster may spend 30 minutes on your roof; a contractor who actually does the work will spend hours assessing what needs to be replaced versus repaired. Get a detailed estimate from a licensed contractor before accepting the insurance company’s offer.
If there’s a significant gap between estimates, some insurance policies include appraisal clauses that allow you to resolve disputes through a neutral third party. In other cases, you may need to involve a public adjuster or attorney.
How to Handle Roof Insurance Claims: The Right Approach
Roof claims are among the most common and most disputed storm damage claims.
Document the damage thoroughly by photographing the entire roof from the ground and, if safe, from a ladder or drone perspective. Contact your insurance company immediately and file your claim with your documentation. Request a timeline for the adjuster’s inspection.
When the adjuster inspects, be present and walk through with them, pointing out all documented damage. Ask them to explain their findings and how they calculated the estimate. Get a copy of the adjuster’s report and estimate before they leave.
After the inspection, get a detailed estimate from a licensed roofing contractor. The contractor will identify damage the adjuster may have missed, including structural issues under the shingles. Compare the two estimates. If there’s a significant difference, contact your insurance company and request a review, providing the contractor’s estimate and asking them to justify any discrepancies.
For roofing claims, watch for depreciation clauses in older policies that reduce your payout based on roof age. Newer policies often include "replacement cost value" (RCV) without depreciation. If you believe the depreciation is unfair, a public adjuster or attorney can help negotiate a better settlement.
Understanding the Ohio Storm Damage Claim Timeline
In Ohio, the typical timeline works like this: you report the claim within 30 days of the loss (insurance.ohio.gov). Your insurer acknowledges receipt within 10 to 30 days. The adjuster inspects within 10 to 30 days. The insurer issues an estimate within 30 days of inspection. You then have 30 days to accept, dispute, or request additional review.
In practice, the process often takes longer due to significant damage or disputes. Weather delays can push timelines back if the adjuster can’t access your roof due to rain or snow.
Keep a written timeline of all communications with your insurance company. Note the date you filed the claim, the adjuster’s scheduled date, the inspection date, and the date you received the estimate. Follow up in writing (email is best) if deadlines are missed. This creates a paper trail that protects you if you need to escalate the claim.
If your insurer unreasonably delays your claim or denies it without justification, you can file a complaint with the Ohio Department of Insurance at no cost. This often prompts an insurer to reconsider their position.
Mistake 6: Making Repairs Before the Adjuster Inspects
Making major repairs before the adjuster inspects can undermine your claim. The adjuster needs to see the damage in its original condition to assess what happened and estimate repair costs accurately. If you’ve already replaced shingles or repaired flashing, the adjuster may assume the damage was less severe and issue a lower estimate.
You do have the right to make temporary repairs to prevent further damage. Tarping a damaged roof, boarding broken windows, and removing debris are appropriate temporary measures. Keep all receipts and photos of these temporary repairs.
For permanent repairs, wait for the adjuster’s inspection and estimate. Once you have the insurance company’s approval and estimate in hand, you can move forward. If the estimate is too low, get a contractor’s estimate first, dispute the insurance company’s estimate, and resolve the discrepancy before starting permanent work.
Exception: if waiting would cause significant additional damage (like active water intrusion causing mold growth), contact your insurance company and ask for permission to proceed with emergency repairs. Get this approval in writing, then submit all receipts and documentation for reimbursement.
Mistake 7: Not Understanding Your Policy’s Deductible and Coverage Limits
Your deductible is the amount you pay out of pocket before insurance coverage kicks in. Common deductibles are $500, $1,000, or $2,500. Some policies have percentage-based deductibles (e.g., 2% or 5% of your home’s insured value), which can be much higher. Coverage limits are the maximum amount your insurer will pay for a particular type of damage.
Review your policy now, before a storm hits. Know your deductible and coverage limits. If you’re underinsured, consider increasing your coverage. If your deductible is very high, you may want to lower it.
When you file a claim, your insurance company will apply your deductible to the settlement. If the adjuster estimates $8,000 in damage and your deductible is $1,000, you’ll receive $7,000. If the damage is close to your deductible amount, it may not be worth filing a claim at all.
Mistake 8: Failing to Keep Detailed Records and Communication Logs
Without organized records, you can lose track of important details, miss deadlines, or struggle to prove what was said and when.
From the moment you file your claim, document every conversation: the date, time, person’s name, and what was discussed. Email is ideal because it creates an automatic record. If you speak by phone, follow up with an email summarizing the conversation.
Keep all documents related to your claim: the original policy, claim form, adjuster’s report, contractor estimates, receipts for temporary repairs, photos of damage, and any correspondence with your insurance company. Create a folder (physical or digital) and organize chronologically. These records become critical if your claim is denied or you receive a low estimate.
Mistake 9: Ignoring Secondary Damage and Hidden Issues
Storm damage isn’t always obvious. Wind and hail can damage a roof in ways that aren’t visible from the ground. Water can seep into walls and attics, causing hidden damage that emerges weeks or months later.
When the adjuster inspects, they may not identify all hidden damage. This is why hiring a licensed contractor to assess the damage is critical. A contractor who will actually perform the repair work has a vested interest in identifying all damage. They’ll look in attics, crawl spaces, and behind walls for water intrusion, structural damage, and signs of mold.
Get a detailed written estimate from your contractor that breaks down all identified damage, including areas that may not be immediately visible. If the contractor identifies damage that the insurance adjuster missed, include this in your dispute of the insurer’s estimate. This can significantly increase your settlement.
Mistake 10: Not Knowing When to Involve a Public Adjuster or Attorney
Most homeowners can navigate straightforward storm damage claims on their own. But some claims become complex if the damage is extensive, the insurer is being unreasonable, or there are coverage disputes.
A public adjuster is a licensed professional who represents policyholders in insurance claims. They work on contingency, taking a percentage of your settlement (typically 10% to 20%) only if they recover money for you. Public adjusters are especially valuable if your claim is denied, significantly underpaid, or involves complex damage assessment.
An attorney is necessary if your claim is denied and you want to pursue legal action, or if there are coverage disputes requiring legal interpretation. Many attorneys handling insurance claims work on contingency, with free initial consultations.
If your insurer denies your claim or offers inadequate settlement, consult these professionals within 30 to 60 days of receiving an unsatisfactory offer.
| Common Mistake | Why It Matters | How to Avoid It |
|---|---|---|
| Waiting too long to file | Policy deadlines and evidence deterioration | Report damage within 30 days |
| Poor documentation | Adjuster may underestimate damage | Photograph from multiple angles, use NAIC app |
| Skipping safety steps | Liability exposure and claim denial | Board windows, tarp roof, document mitigation |
| Unlicensed contractors | No legal recourse, claim complications | Verify Ohio licensing and insurance |
| Accepting first estimate | Underpayment is common | Get contractor estimate, dispute if needed |
| Repairs before inspection | Adjuster can’t verify original damage | Wait for approval, only do temporary repairs |
| Not reviewing policy | Deductible surprises, coverage gaps | Know your deductible and limits before storm |
| Poor record-keeping | Difficult to dispute claims later | Document all conversations and communications |
| Ignoring hidden damage | Secondary damage not covered later | Hire contractor to assess all damage |
| No professional help | Claim disputes go unresolved | Consult public adjuster or attorney if denied |
Storm damage claims are stressful, but avoiding these 10 common mistakes can make the process smoother and increase your settlement. The key is acting quickly, documenting thoroughly, and not accepting the first offer without question. If you’re in Liberty Twp or the Greater Cincinnati area and need professional assessment of storm damage to your roof, siding, or gutters, DGK Home Solutions provides free inspections with detailed documentation to support your insurance claim. Our team has over 20 years of experience helping homeowners navigate the repair process with clarity and confidence. Get a free quote today and let us help you protect your property.
Frequently Asked Questions
How long do I have to file a storm damage insurance claim in Ohio?
Most insurance policies require you to report storm damage promptly, typically within 30 to 60 days of the incident. Ohio law does not specify a strict filing deadline, but delays can complicate your claim and may result in denial if the insurer cannot assess fresh damage. Contact your insurance company immediately after a storm to start the clock. Filing quickly protects your right to coverage and ensures the damage is documented while evidence is still clear.
What should I do immediately after a storm damages my roof?
First, ensure your safety and that of your family. Do not attempt to access the roof if conditions are hazardous. Document the damage with photographs and videos from ground level. Contact your insurance company within 24 to 48 hours to report the claim. Take temporary measures to prevent further damage, such as tarping exposed areas, but do not make permanent repairs until the adjuster inspects. Keep receipts for any emergency repairs. This sequence protects your claim and demonstrates good faith in mitigating additional losses.
Can an insurance company deny a storm damage claim for lack of maintenance?
Insurance companies may deny claims if they determine that poor maintenance directly caused the damage or worsened it. However, normal wear and tear or minor maintenance neglect does not typically void coverage for storm damage. If your insurer denies your claim citing maintenance issues, review your policy language carefully. Consider requesting a second opinion from a public adjuster or attorney, especially if the denial seems unjustified. Many homeowners successfully appeal denials by providing evidence of reasonable property upkeep.
Should I hire a public adjuster for my storm damage claim?
A public adjuster can be valuable if your claim is complex, involves significant damage, or your insurer has underpaid or denied it. Public adjusters work on your behalf and charge a percentage of the settlement, typically 5 to 10 percent. For straightforward, minor claims, you may handle the process independently. However, if you feel overwhelmed or believe your settlement is unfair, a licensed public adjuster in Ohio can negotiate with your insurance company and ensure you receive fair compensation. Always verify their licensing before hiring.
This article was written using GrandRanker